

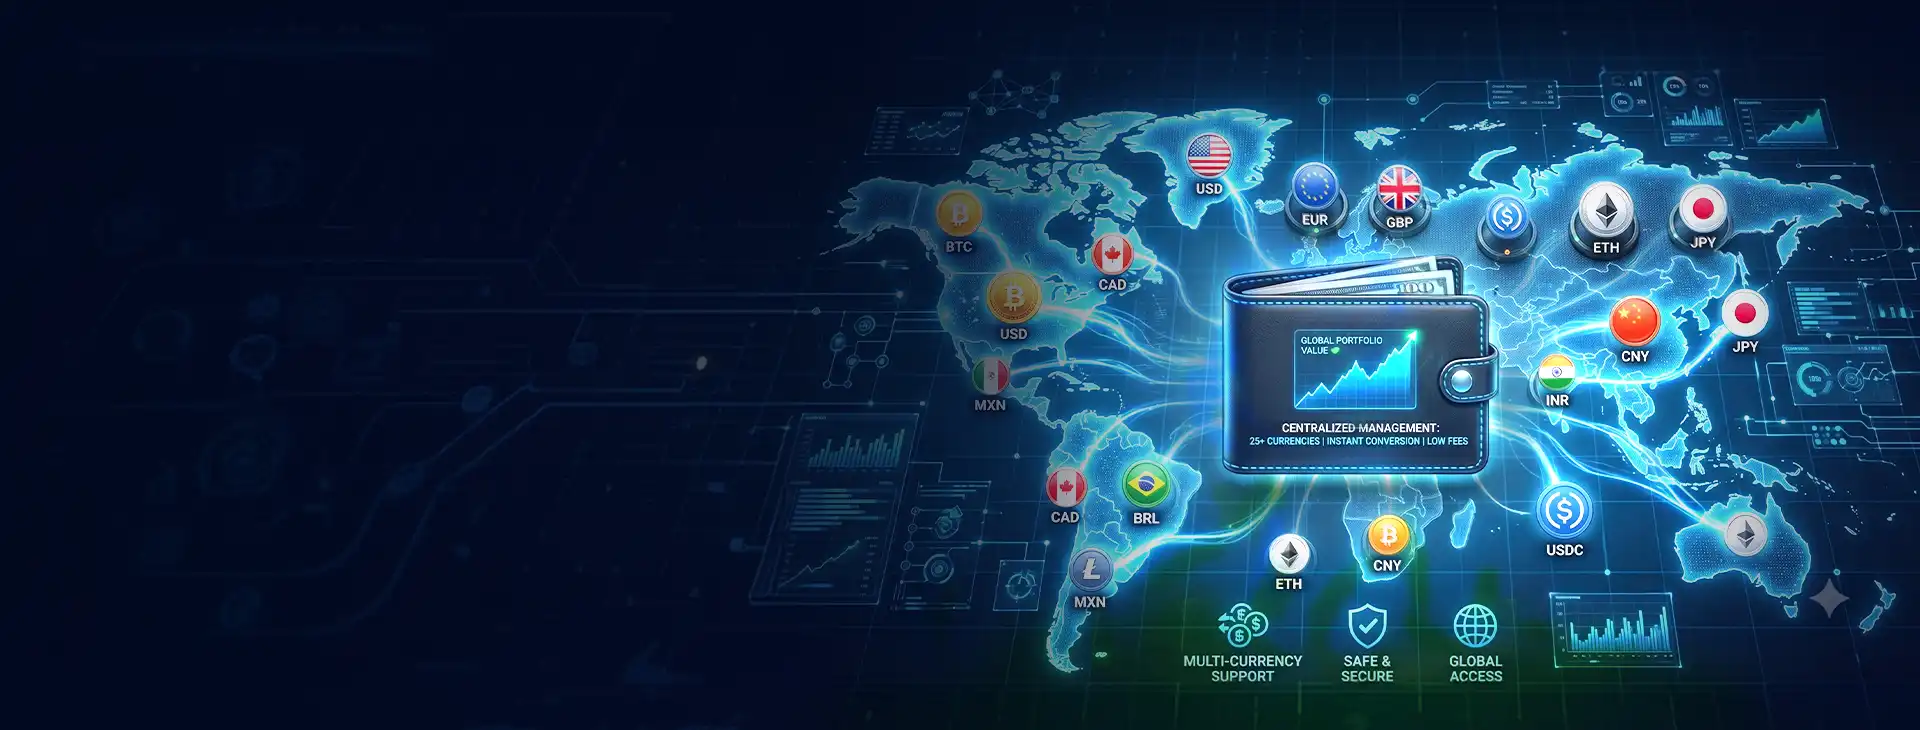
iGAMING PAYMENT GATEWAY & WALLET INTEGRATION
Trusted By
Brands, Studios And Businesses Worldwide
FROM DEPOSIT TO PAYOUT
BUILD THE TRANSACTION LAYER
BEHIND PLAYER FUNDS
Deposits, withdrawals, wallet updates, and provider responses have to remain synchronized across the payment stack. We connect those events through structured transaction states so money can move without losing context between the cashier, PSPs, wallet, and back office.
FOUR CORE WALLET & PAYMENT INTEGRATION AREAS
ARCHITECTED FOR REAL-WORLD iGAMING PAYMENTS
Intelligent
Deposit Routing
A deposit can pass through different gateways, acquirers, and payment rails before it succeeds. Routing logic can evaluate factors such as currency, geography, card BIN, fees, and provider health before selecting the appropriate path.
When a recoverable decline occurs, the request can cascade to a configured secondary PSP while preserving the transaction state and surrounding cashier journey.
Synchronized Wallet &
Ledger States
Credits, debits, holds, reversals, and payouts need to remain consistent across the player wallet, transaction ledger, and back-office records.
Atomic balance updates and double-entry ledger logic keep cash, bonus, withdrawable, locked, and pending-withdrawal states traceable as financial events move through the system.
Automated Withdrawal
& Payout Flows
A withdrawal request can place the requested amount into a reserved state immediately, preventing the same balance from being reused while the payout is pending.
Eligible requests can then move through configured approval and payout workflows to supported bank rails, regional payment methods, or e-wallets while the ledger records each state change.
Idempotency &
Reconciliation
Duplicate callbacks, delayed webhooks, and repeated requests should not result in duplicate credits or debits.
Idempotency controls, payload fingerprinting, replay protection, ledger checks, and reconciliation workflows help match payment events against provider responses and settlement records.
GLOBAL RAILS, LOCAL PAYMENT OPTIONS
CONNECT YOUR CASHIER TO THE PAYMENT METHODS YOUR MARKETS NEED
Cards, instant bank transfers, regional APMs, open-banking rails, and e-wallets can sit behind the same cashier while still following their own provider and settlement flows.
Supported integrations include Visa and Mastercard, Apple Pay and Google Pay, Pix, UPI, SPEI, Interac, SEPA/Open Banking, Skrill, Neteller, MuchBetter, MiFinity, and other payment methods available through the selected provider stack.
Each connection is mapped to its authentication requirements, callbacks, transaction states, and settlement behavior while the wider platform works through a consistent wallet and cashier flow.
CONTROL HOW PAYMENTS MOVE
ROUTING, FAILOVER & PAYOUTRULES BUILT INTO THE FLOW
Connecting a gateway is only the starting point. Routing, fallback behavior, wallet states, verification triggers, and payout rules determine how the payment layer behaves once multiple providers and real player transactions are involved.
BUILT FOR WHAT CHANGES AFTER INTEGRATION
KEEP YOUR PAYMENT STACK
READY TO EVOLVE
A cashier may be hosted, headless, or integrated into an existing platform, but payment methods and provider requirements will continue to change. Modular interfaces make individual connections easier to extend without rebuilding the wider transaction layer.
Frequently Asked Questions
Yes. We can connect payment gateways, wallet services, or cashier workflows to an existing platform, proprietary PAM, third-party system, or legacy backend. Discovery typically starts with the current APIs, wallet model, transaction states, provider connections, and back-office dependencies.
Yes. A hosted cashier can be delivered through an embeddable interface such as an iFrame or drop-in component, while a headless integration exposes payment and wallet functionality through APIs so your team can retain control of the checkout experience.
Useful inputs include provider documentation, sandbox or test credentials, authentication requirements, existing platform APIs, wallet behavior, target markets and currencies, and the transaction states already used by the platform. Missing dependencies can be identified during technical discovery.
The architecture can use idempotency keys, payload fingerprinting, transaction references, locking, ledger checks, and reconciliation processes so repeated requests or callbacks do not execute the same financial event twice.
Yes. Withdrawal workflows can reserve funds, apply configured approval or verification conditions, and route eligible payouts to supported bank rails, regional payment methods, or e-wallets. Each state change remains connected to the corresponding wallet and transaction record.
KYC and AML systems can operate as conditional integrations around the transaction flow. Depending on the operating model, verification can be triggered by withdrawals, cumulative thresholds, or other review events rather than being embedded into every cashier action.
The implementation depends on the chosen cashier model and providers. Hosted payment components can reduce direct exposure to card data, while integrations can also use signed callbacks, controlled access boundaries, provider authentication, and other safeguards supported by the selected payment and verification systems.
The main factors are the existing platform and wallet architecture, number of PSPs and payment methods, target markets and currencies, routing and failover requirements, payout workflows, reconciliation needs, verification integrations, and the quality of available provider APIs and sandbox environments.
READY TO BUILD OR
EXTEND YOUR PAYMENT STACK?
Get a reply within 24 hours
Tell us where the project stands today. We'll start there.


 Book An Appointment
 WhatsApp